

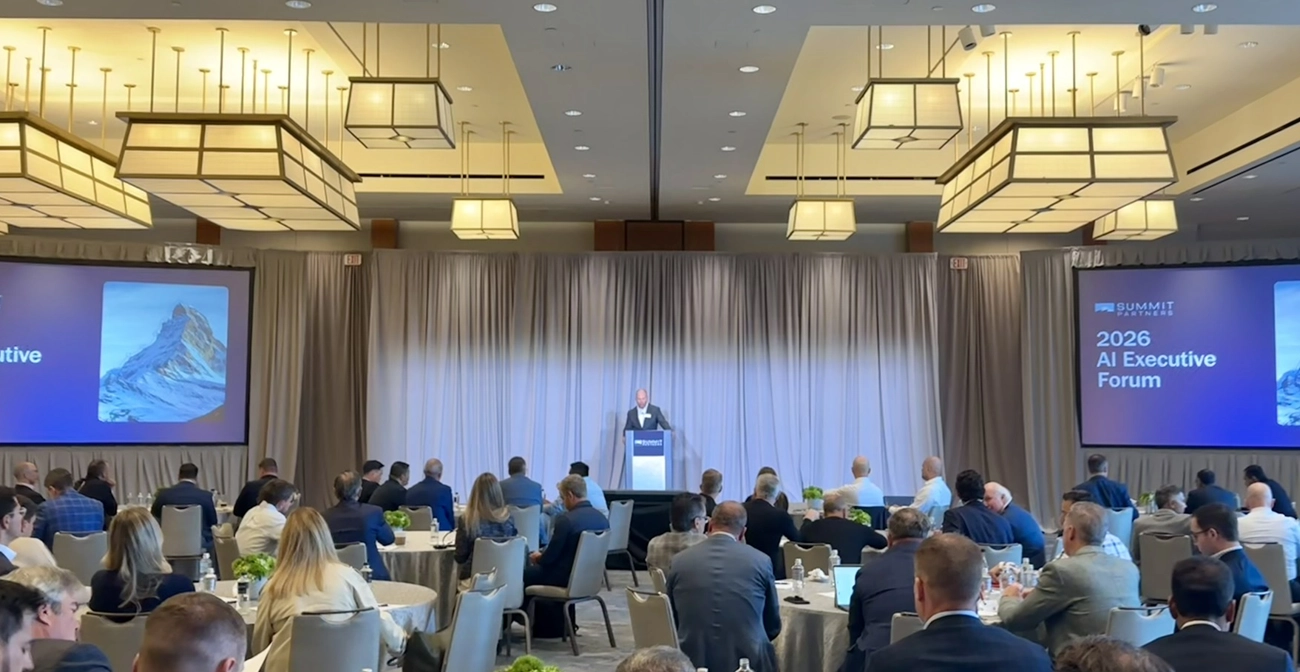
On September 1–2, Summit Partners hosted its 2026 Executive AI Forum in Boston, bringing together roughly 90 executives from across our U.S. portfolio for two days of peer sessions, working tracks and outside speakers.
Among the many topics discussed, one theme stood out and framed much of the conversation: the gap between AI adoption and measurable P&L impact. Adoption is no longer an open question. Nearly every company in our portfolio now reports AI activity.(1) The same trend is visible more broadly. In McKinsey’s 2026 global survey of more than 1,700 organizations, nearly nine in ten report regular AI use in at least one business function, and 44% say AI is now scaling across the enterprise, but only 37% attribute any EBIT impact at all to AI and just 6% report that AI contributes 5% or more to EBIT.(2)
We believe the differentiator is what sits underneath that activity. Our portfolio data show that companies with a named owner, a constraint target and a focus on rebuilding processes around that constraint were roughly three times more likely to report a positive, measurable P&L impact.(3) McKinsey's researchers draw the same conclusion: returns follow organizational change, not tool deployment alone.(2)
We have seen this pattern before: general purpose technologies have rarely delivered on the timeline their buyers expected, and AI is still early. Two days in Boston offered us a closer look at companies already closing the gap between AI adoption and impact, and what they did to get there.
What history suggests
In 1987, economist Robert Solow observed that you could see the computer age everywhere but in the productivity statistics.(4) While the PC was introduced in 1981, the payoff did not arrive until roughly a decade later. Federal Reserve economists found that U.S. labor productivity growth held at roughly 1.5% a year in the early 1990s and then rose to 2.6% after 1995, with advancements in information technology explaining about two-thirds of the jump, concentrated in the industries that had invested a decade earlier.(5) Electricity followed the same arc over a longer horizon: factory output moved little until managers redesigned the floor around the new technology.(6)
Economists formalized this pattern in 2021 as the productivity J-curve: when a general-purpose technology arrives, companies spend years on complementary investments in process redesign, training and new roles, during which output looks flat while the foundation gets built.(7) There is an important caveat, however. The J-curve applies only to companies that are making these investments. Unused licenses, or used licenses without related investment in process and people, are a cost with no curve behind them.
Current data provide additional context. An MIT report from July 2025 argued that only 5% of custom-built enterprise AI tools reached production with sustained impact (a figure the report itself describes as rough and interview-based).(8) IDC's 2026 survey waves show the share of organizations stuck at the pilot stage shrinking while production deployment rises.(9) Taken together, we read these dynamics as the middle of a J-curve, rather than the end of a hype cycle.
Turning AI adoption into results: Insights from the portfolio
The Forum's peer sessions offered a close look at companies making complementary investments needed to help advance along the productivity J-curve and turn AI adoption into results: process redesign, platform governance and data readiness. They came at it from different directions, but each had rebuilt something before expecting a return from it. Three themes recurred, and in our experience, they apply well beyond the companies in the room.
Find the constraint before you build.
A healthcare services company traced most of its prior-authorization inefficiency to a single point: documentation gaps at submission. Rather than deploying AI broadly, it built an internal review tool for use precisely at that moment of submission and reported roughly 40% fewer requests for additional information, along with a 28% reduction in turnaround time across more than 12,000 cases.(10)
Build platforms to decentralize AI ownership beyond technology teams.
Two software companies came at the problem from the opposite direction. Their pain points were individually too small for enterprise technology projects. Instead of waiting for one big enough, they built a single governed template that business teams could build on, with shared identity, version control and deployment patterns — shifting the unit of investment from the use case to the foundation underneath it.
The bottleneck is usually people and data, not tools.
Two others reported the same finding from inside their engineering organizations. They had licensed capable tools, but what limited their pace was how consistently engineers actually used them and how easily they could reach the data they needed. Both moved their effort from evaluating tools to driving adoption and opening up data access.
The starting points differed, but the pattern was consistent. Each company invested in process redesign, platform governance or data infrastructure before expecting results. That matches our own portfolio data, which show that companies with this discipline in place are more likely to report a P&L-tied result.(3)
The market is drawing the same conclusion
External confirmation comes from what the AI labs themselves began selling this year. In May, OpenAI launched a deployment business built around forward-deployed engineers whose stated job is to embed themselves inside customer organizations and redesign workflows; Anthropic launched a services offering aimed at mid-sized companies without large internal AI engineering teams. Accenture booked $5.9 billion in generative AI work in fiscal 2025.(11) Gartner's latest forecast puts worldwide AI services spending at $576 billion in 2026, well above the $461 billion forecast for AI software.(12)
In our view, the people closest to the technology are betting that the gap between adoption and measurable transformation is large and closable primarily with labor, the same conclusion we heard from many leaders at our Boston Forum.
The counterpoints worth taking seriously
Two counterarguments deserve mention. The first: perhaps the gap between adoption and transformation is overstated. Data from several surveys, including Anthropic’s “2026 State of AI Agents” report, indicate far more upbeat results than independent surveys suggest.(13) While the samples and the incentives differ, it is a good reminder that there is a range of data sets in the market.
Second: the magnitude of the eventual payoff is debated. MIT economist Daron Acemoglu argues the gains may stay small, under 1% of total factor productivity over a decade, because the economically valuable remaining tasks are the hard ones.(14) Stanford economist Erik Brynjolfsson, however, expects far more, far sooner.(15) Both are forecasts, and they disagree by an order of magnitude. Individual companies cannot resolve that dispute, but they can make it largely irrelevant to their own decisions by measuring their own results: a number net of tool cost, reproducible from a source system.
Two questions for the year ahead
For leaders of growth-stage companies, the practical questions coming out of the Forum are direct ones:
1. What are your AI budget priorities for 2027?
2. How, specifically, will your leadership team and board measure P&L impact?
The companies that presented in Boston could answer both questions with a specific process and a measured result. We believe that discipline, more than any particular tool choice, will separate the growth companies that close the gap from those that simply adopt.
In the coming weeks, we will share more of what we learned, including the next edition of Summit Partners' quarterly AI trends series. For a broader look at how we think about AI in growth companies, see AI for Growth Companies: Strategies, Insights and Use Cases.
Growth Timeline
Don't delete this element! Use it to style the player! :)


Related Experience
About the Authors
Related Content

Sources and Disclosures
(1) Reflects information gathered by Summit Partners from multiple portfolio sources, including responses from over 100 active portfolio companies to a survey conducted by Summit Partners during Q2 2026 together with information obtained through board participation, periodic financial and operating reports, vendor usage data and ongoing dialogue with portfolio company management. AI activity was self-identified by each company or observed by Summit through the sources described above and encompasses a broad range of uses, including internal productivity and workflow tools, AI applied to internal operations or engineering and AI capabilities embedded in customer-facing products. No minimum threshold of scale, revenue contribution or production deployment was applied and responses may not be directly comparable. Such information is self-reported or anecdotal in nature and has not been independently verified by Summit in every instance. Results are not representative of the experience of the broader market and are not indicative of investment performance or future results.
(2) McKinsey & Company, “The state of AI in 2026: On the road to ROI,” Global Survey, August 25, 2026.
(3) Based on responses from over 100 active portfolio companies to a survey conducted by Summit during Q2 2026, together with supplemental information obtained through ongoing dialogue with portfolio company management. Whether a company had a named individual accountable for AI strategy was asked directly in the survey; the presence of a constraint target and of process redesign around that constraint was inferred by Summit from companies' qualitative survey responses and supplemental information rather than asked as discrete survey questions. "Positive, measurable P&L impact" refers to a self-reported, measured revenue or cost outcome. The approximately “three-times” comparison reflects the relative frequency of such reported P&L impact among companies exhibiting these characteristics versus the responding population overall; it is based on a limited number of respondents, reflects self-reported and non-standardized measurement methods, and describes an observed association rather than a causal relationship. The underlying information reported by portfolio companies has not been independently verified by Summit; the comparison reflects Summit's own analysis of such self-reported information. Such analysis is not representative of the experience of the broader market and is not indicative of investment performance or future results.
(4) Robert Solow, The New York Times Book Review, July 12, 1987.
(5) Oliner & Sichel, Federal Reserve, 2000; Basu, Fernald, Oulton & Srinivasan, 2003.
(6) Paul David, “The Dynamo and the Computer,” American Economic Review, May 1990.
(7) Brynjolfsson, Rock & Syverson, “The Productivity J-Curve,” AEJ: Macroeconomics, January 2021.
(8) MIT NANDA, “The GenAI Divide: State of AI in Business 2025”, July 2025.
(9) IDC, “From Pilot to Production—How Rapidly is AI Agent Adoption Maturing?”, June 2026.
(10) Statistics herein are based on unaudited company-provided data comparing results measured before and after deployment of the company's internal review tool. Such data have not been independently verified by Summit Partners and no representation is made as to accuracy or completeness.
(11) Accenture Q4 FY2025 Earnings Presentation, September 25, 2025.
(12) Gartner, "Gartner Forecasts Worldwide AI Spending to Grow 49.5% in 2026," September, 16, 2026.
(13) Multiple sources: Anthropic, “The 2026 State of AI Agents Report,” December 11, 2025; MIT, “The GenAI Divide: State of AI in Business 2025,” July 2025; Deloitte, “State of AI in the Enterprise: The Untapped Edge,” January 2026; PricewaterhouseCoopers, “PwC’s 29th Global CEO Survey: Leading through uncertainty in the age of AI,” January 2026; Gartner, “Gartner Survey Finds Only 22% of Organizations Have Successfully Scaled AI Across Multiple Business Units,” September 2026.
(14) Acemoglu, “The Simple Macroeconomics of AI,” Economic Policy, 2025.
(15) Brynjolfsson, Harvard Business School interview, March 2025.
The content herein reflects the views and opinions of Summit Partners and is intended for executives and operators considering partnering with Summit Partners. References to specific portfolio companies and their reported results are provided for illustrative purposes only, were selected based on relevance to the topics discussed at the 2026 Executive AI Forum (the “Forum”) and not on the basis of performance, and are not representative of all Summit Partners portfolio companies or investments; reported results are self-reported by the companies involved. The information herein, including information based on or derived from third-party sources believed to be reliable, has not been independently verified by Summit Partners or an independent party, and Summit Partners makes no representation or warranty as to its accuracy or completeness. Such content and information should not be construed or relied upon as an indication of future results or other future outcomes. This content is provided for informational purposes only and does not constitute, and should not be construed as investment, legal, tax or other advice, or an offer to sell, or a solicitation of an offer to buy, any security or investment product.
The information herein contains forward-looking statements and projections, including statements regarding market trends, anticipated outcomes of AI deployments, the potential benefits of AI adoption, the expected timing and magnitude of AI-related productivity gains and third-party forecasts and projections reproduced herein. Forward-looking statements are based on current expectations, assumptions and beliefs of Summit Partners as of the date hereof and are subject to known and unknown risks, uncertainties and other factors that may cause actual results, performance or outcomes to differ materially from those expressed or implied. Such statements reflect Summit Partners' views as of the date of publication and Summit Partners undertakes no obligation to update or revise any forward-looking statement to reflect new information, subsequent events or changed circumstances. Forward-looking statements should not be relied upon as a guarantee, prediction or definitive statement of fact, and are not intended to represent projections of future fund performance or returns. Past observations and outcomes described herein are not necessarily indicative of future results.
Get the Latest from Summit Partners
Subscribe to our newsletter to stay up to date on our partners, portfolio, and more.